Embedded Payments Versus Payment Gateways
Compare embedded payments versus payment gateways for membership businesses and choose the payment model that improves collections, control, and revenue.
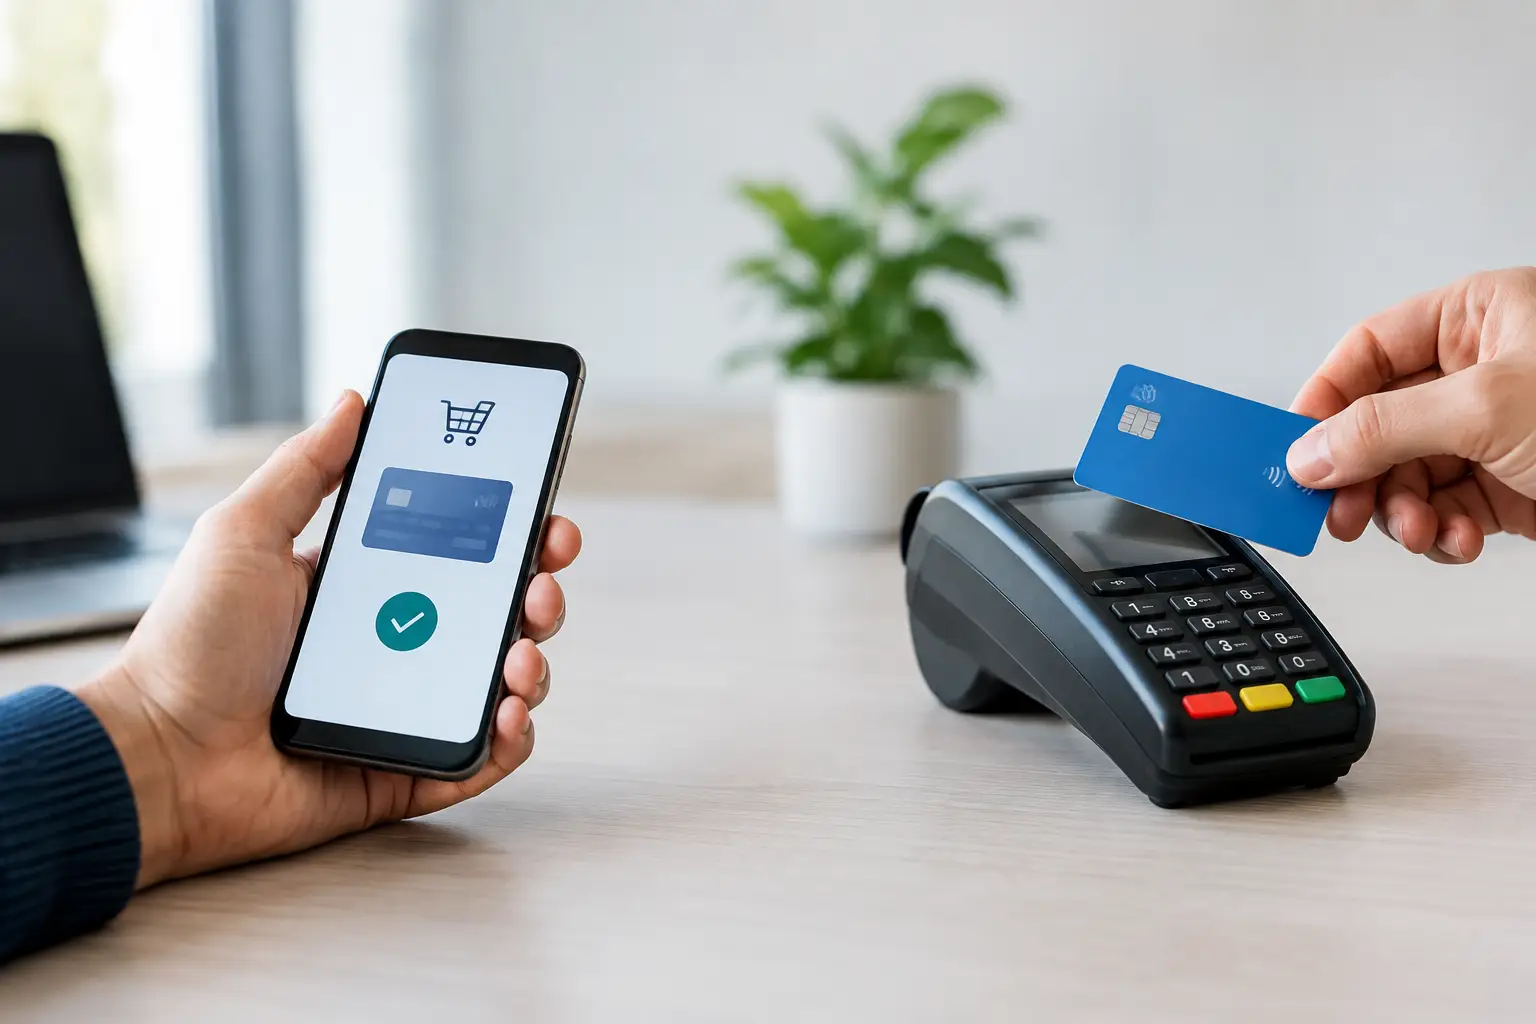
A declined membership payment is never just a declined payment. It can trigger a front-desk conversation, a manual follow-up task, a paused membership, and a gap in the revenue report. For gyms, martial arts academies, and fitness studios, the choice between embedded payments versus payment gateways directly affects how much of that work is automated, how clearly teams can see the outcome, and how reliably recurring revenue lands.
The terms are often used interchangeably, but they describe different approaches to taking payments. The right choice depends on your operating model, the systems your team uses every day, and whether payment processing is treated as a separate utility or a core part of your revenue operation.
What Is a Payment Gateway?
A payment gateway is the technology that securely sends payment information from your website, point of sale, or billing software to the payment processor and card networks. Think of it as a secure connection point between your business and the systems that authorize a card, bank transfer, or digital wallet payment.
A gateway can support one-time purchases, invoices, recurring billing, card-on-file transactions, and online checkout. It may be connected to your membership platform through an integration, or it may operate independently, requiring staff to reconcile transaction data across multiple systems.
For a membership business, a gateway can be a practical option when you already have established billing software, a preferred processing relationship, and internal processes that handle reporting and exceptions well. The trade-off is that a gateway alone does not manage memberships, automate dunning workflows, update account records, or tell the front desk what action to take after a failed charge. Those capabilities must come from the surrounding software.
What Are Embedded Payments?
Embedded payments place payment processing directly inside the software your team uses to run the business. Rather than moving between a membership system, a payment portal, a terminal application, and a separate processor dashboard, staff manage transactions where memberships, attendance, invoices, and member records already live.
This model is especially valuable for recurring-revenue operations. When a member changes cards, misses a payment, signs a new agreement, buys retail items, or upgrades a plan, the payment event can immediately update the same account record used by the front desk and management team.
Embedded payments are not simply a checkout button placed inside an app. At their best, they connect payment data to operational workflows: automated recurring charges, payment reminders, failed-payment recovery, stored payment methods, receipts, refund controls, reporting, and permissions. That connection reduces the manual handoffs that create missed follow-up and incomplete financial records.
Embedded Payments Versus Payment Gateways: The Core Difference
The clearest distinction is ownership of the workflow. A payment gateway moves payment data between systems. Embedded payments make processing part of the business system itself.
With a gateway-based setup, your team may need to confirm whether a payment posted, then return to the membership platform to update an account or remove a billing hold. With embedded payments, the transaction status and the member status are designed to move together. A successful charge can keep a membership active. A failed charge can initiate a reminder sequence, flag the account for staff, and feed directly into collections reporting.
Neither approach is automatically better in every situation. A gateway may offer more flexibility for businesses with specialized technology stacks or existing processor contracts. Embedded payments are usually stronger when efficiency, visibility, and repeatable member workflows matter more than managing several disconnected vendor relationships.
Why Payment Architecture Matters for Membership Revenue
Membership businesses do not process payments in isolated moments. They process them across recurring dues, enrollment fees, retail sales, private training, events, late fees, family accounts, and account changes. Every exception creates operational work.
When payment processing sits outside the primary operating system, staff often become the bridge between tools. They check a processor portal, search for a member, update notes, retry a charge, and explain the status to the customer. This may work at low volume, but it becomes expensive as membership counts, locations, and team size grow.
An embedded approach turns more of these events into defined workflows. A new member can sign an agreement, add a payment method, enroll in recurring billing, and receive confirmation from one record. A manager can see collection performance without exporting multiple reports. Authorized staff can issue a refund or review transaction history without gaining broad access to every financial setting.
That visibility matters because revenue leakage is rarely caused by one large problem. It comes from small gaps: expired cards that were never updated, failed charges that were not retried, canceled members still being billed, cash payments that were not recorded correctly, and reports that do not match the accounts at the front desk.
Where Payment Gateways Can Make Sense
A standalone or separately integrated gateway can be a sensible choice when your business has complex requirements outside its core membership platform. For example, an organization may have a custom website, a separate e-commerce operation, or a finance team that needs to maintain a particular processing relationship.
It can also make sense if your software supports a gateway integration that reliably synchronizes key payment details. The question is not whether the gateway can authorize payments. Most can. The question is whether the integration keeps account status, payment history, recurring billing rules, refunds, and reporting accurate without adding manual work.
Before selecting this route, operators should clarify who owns support when something fails. If a charge appears in one system but not another, who resolves it? If a member’s plan is paused, does recurring billing pause automatically? If a dispute occurs, can your team access the necessary account history in one place? Those answers reveal the real operational cost of a disconnected setup.
Where Embedded Payments Create an Advantage
Embedded payments are built for operators who want the payment function to reinforce the rest of the business. The major advantage is not that staff can accept a card payment from the same screen. It is that payment data can drive faster, more consistent action across the member lifecycle.
For a martial arts academy, that may mean connecting billing status with attendance, rank progression, family memberships, and signed agreements. For a multi-location gym, it may mean giving site managers access to the data they need while preserving centralized control over revenue reporting and payment permissions. For a studio, it may mean reducing the number of overdue accounts that require a personal call from the owner.
A system such as BillingLogix can combine recurring billing, POS activity, member account management, check-in, invoicing, and payment processing in one operating environment. That structure helps teams reduce duplicate entry, manage collections from live account data, and make financial decisions from reports that reflect what is happening on the floor.
Embedded payments can also support more intentional processing-cost strategies. Businesses may choose to absorb fees, adjust pricing, use compliant zero-processing-fee programs where appropriate, or steer certain payment types toward lower-cost options. The right model depends on local rules, customer expectations, and your pricing strategy, but the reporting must be clear enough to measure the impact.
Questions to Ask Before You Choose
Start with the workflows that consume staff time, not the payment feature list. Track what happens after a failed recurring payment, a card expiration, a refund request, a membership freeze, and a chargeback notice. If employees routinely jump between systems to complete those tasks, integration depth should be a decision priority.
Next, look at reporting. You should be able to answer practical questions quickly: Which locations have the highest past-due balance? Which payment methods have the most failures? How much revenue is scheduled to bill this week? Which staff member processed a refund? If those answers require spreadsheets and portal logins, your payment setup is limiting management visibility.
Finally, consider scale. A single-location business may tolerate a few manual steps. A growing organization with multiple locations, role-based teams, and thousands of recurring transactions needs controlled workflows, reliable audit history, and consistent data. Choosing the cheaper-looking option at the start can cost more if it creates administrative labor and collection problems later.
Build Payments Around the Member Experience
Members do not care whether your back office uses a gateway or embedded processing. They care that enrollment is easy, receipts arrive promptly, recurring charges are predictable, and billing questions can be answered without being transferred between departments.
Choose the model that gives your team the clearest view of each member and the fastest path to resolve payment issues. When billing, membership management, and reporting operate from the same source of truth, your staff spends less time chasing transaction details and more time building a business members want to stay with.